For decades, the industry’s default guideline for managing living annuities has been the 4% withdrawal rule. The rule is a guideline suggesting that if retirees initially withdraw around 4% to 5% of their investment value as starting income and adjust it yearly for inflation, their income will last for 25 to 30 years.
But in a landscape defined by high inflation, rising living costs, and volatile markets, sticking to this rule is becoming increasingly difficult for most retirees.
At a time when retirees are living longer and market uncertainty remains constant, it is vital to help stretch their retirement savings without pushing them into too high-risk, market-linked asset classes to chase unrealistic returns. Instead of simply encouraging retirees to take on more investment risk, the focus should shift towards structural solutions that help retirement savings go further while providing greater financial certainty.
The maths behind the rule of thumb
A rule of thumb is a useful, practical guide for making quick, approximate decisions when exact information is not available. In the context of a living annuity, the maths behind the 4% to 5% guideline has a very specific assumption about the investment returns required to sustain it.
If we assume a standard inflation adjustment of 5% on a retiree’s income every year, we can calculate the exact net-of-fee investment return required to keep the full income flowing for 25 years at different drawdown levels:
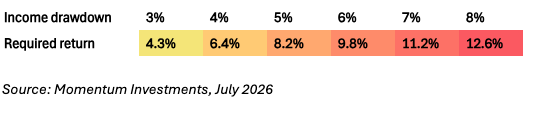 At an initial drawdown of 5%, a retiree needs a consistent, net-of-fee return of 8.2% per year. For many, this is a realistic long-term expectation in the South African market.
The challenge emerges when a client’s capital is insufficient, forcing them to draw slightly more. If a retiree needs to draw 6% to cover their expenses, the required return immediately jumps to nearly 10% net of fees. To sustain a 7% or 8% drawdown over more than two decades, they require double-digit returns year after year.
These net-of-fee return levels are not consistently achievable in real-world markets without taking on levels of equity risk that may be inappropriate for a retiree.
The capital reality check
To understand why so many South African retirees are forced to break this rule of thumb, we need to consider the capital required to generate a basic living wage at a safe 5% drawdown rate:
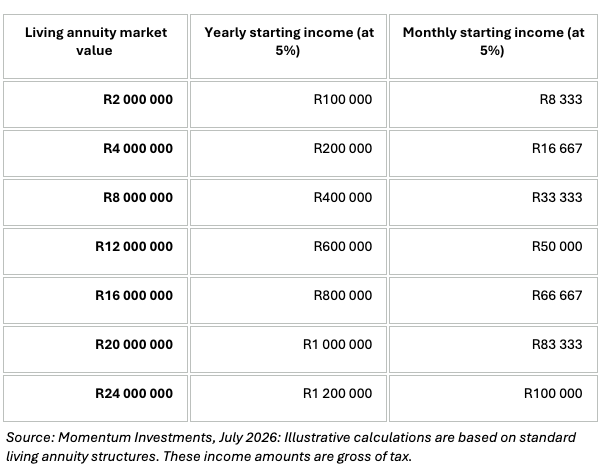 Because of the savings shortfall facing the vast majority of South Africans, the capital required to secure a comfortable middle-class income under the 5% rule has become astronomical.
Consequently, many retirees have no choice but to break the rule of thumb. They draw 6%, 7%, or more of their capital from day one, implicitly betting their financial survival on the hope that their market-linked investment funds will deliver high single-digit or double-digit net returns indefinitely. This exposes them to longevity risk – the very real danger of outliving their capital.
How the power of a blended structure lowers the investment hurdle
Consider a 65-year-old man investing R2 million and who requires a starting drawdown of 6.0% (escalating at 5% per year to maintain purchasing power). In a 100% market-linked living annuity, a 6.0% drawdown would require a yearly return of just under 10% net of fees to maintain the full income to the age of 90, after which his income will start to fall as he reaches the maximum 17.5% income limit.
However, if that same retiree allocates 50% of his portfolio to Momentum Wealth’s guaranteed lifetime income component (called the Guaranteed Annuity Portfolio) and keeps the other 50% in market-linked assets, the financial dynamics shift.
Because the guaranteed component secures a stable, lifetime income that is typically higher than standard ‘safe’ withdrawal rates, the burden on the remaining market-linked portion of the portfolio is significantly reduced. In this blended scenario, the retiree can sustain the initial 6.0% drawdown even if his market-linked assets perform at 8.0% net of fees*.
Designing for continuity
Stretching retirement savings is not about finding a brilliant asset manager who can guarantee double-digit returns during market downturns. It’s about restructuring the retirement portfolio so that the maths works for you, rather than against you.
By combining the growth potential of market-linked investments with the structural safety net of guaranteed lifetime income, financial advisers can build retirement plans that protect against longevity risk while maintaining flexibility. This blended approach ensures that the retirement conversation shifts from a defensive lecture on self-deprivation to a proactive strategy for lifelong financial continuity.
Visit momentum.co.za to learn more about Momentum Wealth, its living annuity and the Guaranteed Annuity Portfolio.
*Assumption for the Guaranteed Annuity Portfolio: A starting income of R5 990 per month (escalating at 5% every year), this was the income available as of July 2026.

Momentum Wealth is part of Momentum Investments and Momentum Group Limited. Momentum Wealth (Pty) Ltd is an authorised financial services provider (registration number 1995/008800/07, FSP number 657). Momentum Metropolitan Life Limited is an authorised financial services and credit provider (registration number 1904/002186/06, FSP number 6406).
Guaranteed Annuity Portfolio
The information in this article is for general information purposes and not an invitation or solicitation to invest. The information is not intended to be accounting, tax, investment, legal or other professional advice or services as set out in the Financial Advisory and Intermediary Services Act 37 of 2002 (FAIS), or otherwise. The information in this article, including opinions expressed, is derived from proprietary and non-proprietary sources that Momentum deems reliable. It is not necessarily all-inclusive but is accurate at the publication date. While we make all reasonable attempts to ensure the accuracy of the information in this article, neither Momentum Wealth (Pty) Ltd, Momentum Metropolitan Life Limited, nor any of their respective subsidiaries or affiliates make any express or implied warranty about the accuracy of the information in this article.
Past performance is not necessarily a guide to future returns. Financial advisers should conduct a suitability analysis and due diligence with clients on the investments mentioned in this article as part of their investment mandate and investment advice process. Terms apply. Available from your financial adviser and Momentum.
The Retirement Income Option and Guaranteed Annuity Portfolio are life insurance products, underwritten by Momentum Metropolitan Life Limited, a licensed life insurer under the Insurance Act.