Following years of negative sentiment, the FTSE/JSE All Bond Index delivered 17.18% in 2024 and a further 24.24% in 2025. With inflation remaining well contained, this translated into real returns of 14.18% and 20.64% for the respective calendar years – remarkable figures when set against the long-term expected real return of roughly 5%. Active bond managers added further value, outperforming the index in both periods at 18.24% and 25.03% respectively (Alexforbes Bond Survey)..
We decomposed the returns of the average bond manager in the Alexforbes Bond Survey using the capital asset pricing model (CAPM) represented in Equation 1. The risk-free rate is proxied by the overnight rate. Systematic returns reflect the beta-adjusted returns of the market above the risk-free rate. Active duration captures the incremental return from duration positioning relative to the index.
Active rolldown measures the incremental return from the curve-weighted rolldown effect, based on active weights relative to the structural rolldown. Curve positioning reflects returns attributable to active weights across the yield curve, while other active strategies encompass security selection, credit, trading and additional sources of alpha.
Equation 1: Bond manager capital asset pricing model
ReturnP = Rf + Systematic Return + Active Duration + Active Rolldown + Curve Positioning + Other Active Strategies + Error
Table 1 presents the results of these regressions. Beyond the systematic return component, curve positioning and other active strategies make the greatest contribution to returns across both periods. This indicates that the alpha generated was driven by deliberate active investment strategies, rather than simple duration bets. An alpha p-value of 0.0065 over the five-year period further confirms that local bond managers are skilled at generating alpha above the index, at a 99% confidence level.
Table 1: Bond manager capital asset pricing model return contributions (annualised)
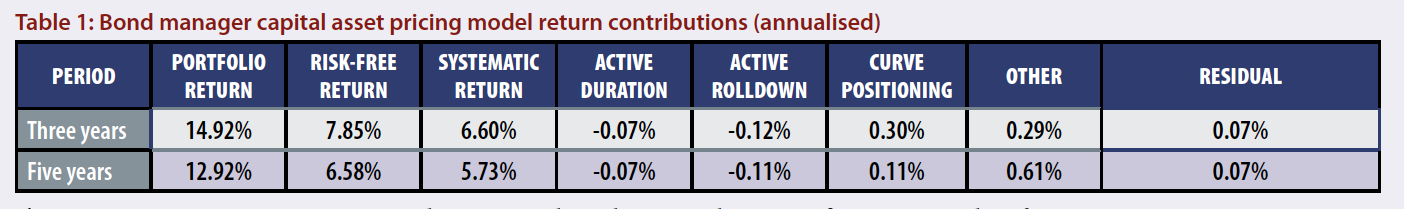
Three-year regression statistics: R-squared = 0.9981, Adjusted R-squared = 0.9980, β =1.0262, ρ-value of α = 0.0883
Five-year regression statistics: R-squared = 0.9973, Adjusted R-squared = 0.9972, β =1.0275, ρ-value of α = 0.0065
Source: Independent Investment Solutions
We can isolate the active returns further using Equation 2, which removes the market return (including the risk-free rate) and attributes alpha to the same strategies described above.
Equation 2: Bond manager active return contributions
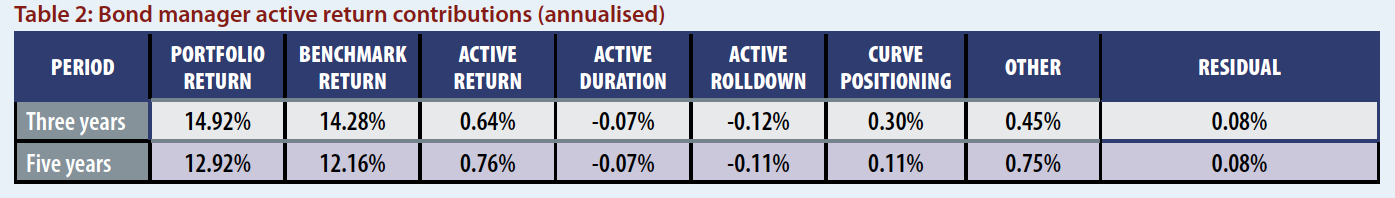
Table 2 presents the results of this arithmetic decomposition. Consistent with the regression findings, curve positioning and other active strategies account for the greatest return contribution across both periods.
Table 2: Bond manager active return contributions (annualised)
Source: Independent Investment Solutions
There are two key takeaways from this analysis. Firstly, the average local bond manager demonstrates genuine skill in generating alpha above the FTSE/JSE All Bond Index, particularly over five years. Secondly, most of this alpha is attributable to active strategies beyond simple duration overweighting – a clear indication of breadth and depth in active management.